 Vietnamnet.vn

 Podcast


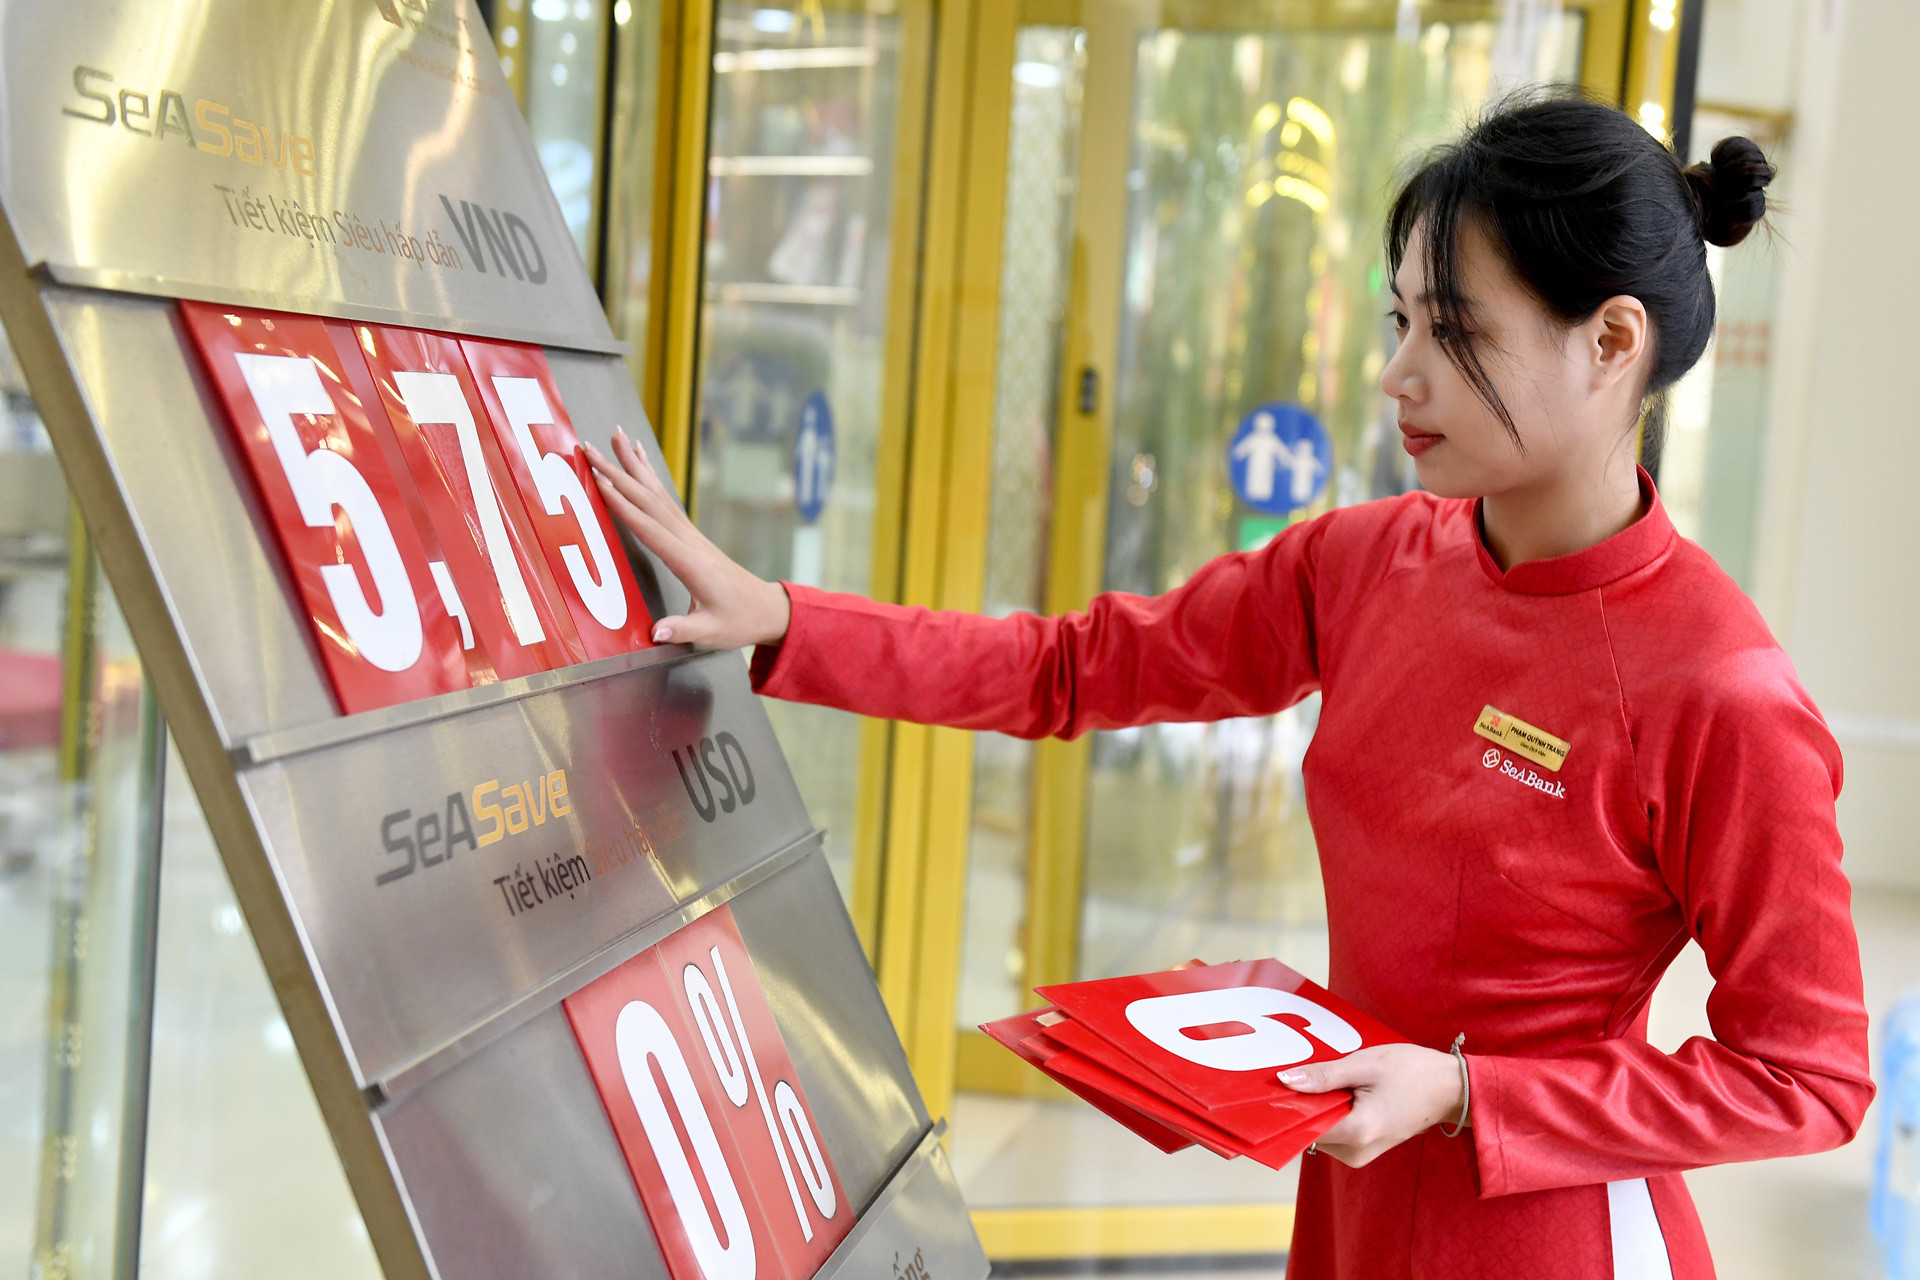
Commercial banks are collectively lowering deposit rates and rolling out interest rate reduction programs for loans. At the October 19 meeting between the State Bank of Vietnam (SBV) and commercial bank executives, Dao Minh Tu, Vice Chair and Secretary General of the Vietnam Banks Association, acknowledged that bank lending rates remain high relative to businesses' profit-generating capacities.
To bring down lending rates, alongside banks' internal operational cost-cutting efforts, a prerequisite is that input rates must genuinely decline. This is why Le Ngoc Lam, Chair of BIDV, called on banks to make a real reduction of about 0.5 percentage points in deposit rates to help lower the overall lending rates.
Nguyen Van Phuong of the University of Economics, Vietnam National University, Hanoi, said cutting interest rates is necessary to reduce financial costs, support production and prevent unhealthy competition for deposits among banks.
The policy is more feasible now that funding pressures have eased. As of the end of last week, deposits had grown 11.22 percent, while credit had expanded 11.44 percent. The two growth rates are now relatively close, but that alone does not mean every bank has ample funding.
However, Phuong stressed that interest rate cuts must be genuine. Businesses need to benefit from lower borrowing costs and concessions that last long enough, without having to offset the savings through fees or additional conditions.
“A program may be announced on a grand scale, but if little money is actually disbursed or the preferential rates last only for the first few months, it cannot be considered a success,” Phuong said.
Stable funding at a reasonable cost is a necessary condition for reducing lending rates. To sustain the cuts, banks must also manage risks effectively and reduce operating expenses.
“We need to look squarely at the gap between the two reductions. A 0.5-percentage-point cut in deposit rates does not automatically create enough room to lower lending rates by 1.5-2 percentage points. Deposits raised previously must still be paid according to existing contracts, so average funding costs decline only gradually as older deposits mature. The remaining reduction in lending rates must come from banks' profits, lower costs or reduced risks,” he said.
For example, if a bank cut its lending rate by 1.5 percentage points on an outstanding loan portfolio of VND10 trillion and maintained the reduction for a full year, its interest income would fall by around VND150 billion, before accounting for any savings from lower funding costs.
The example highlights the need to specify the volume of outstanding loans covered, the duration of the cuts and how they will be financed, rather than simply pledging a percentage reduction.
“A bank's profit plan is a management target, not an immutable objective that should be used to refuse to share borrowers' difficulties. However, banks must not be forced to cut income to the point that their ability to make provisions and strengthen capital is undermined. Boards of directors need to adjust profit expectations when necessary while protecting long-term financial strength,” Phuong said.
Meanwhile, the watchdog agency should reduce lending risks by resolving legal obstacles affecting projects, addressing outstanding debts, improving the quality of business data and strengthening credit guarantees. When borrowers have healthier cash flows, banks can reduce risk premiums without lowering credit standards.
How to avoid bargaining over interest rates when depositing?
After several rounds of recent deposit rate cuts, banks quickly returned to the race to raise interest rates. Some banks even offered actual rates above their published schedules, disclosing the higher rates only to individual customers.
This reality demonstrates that banks cannot sustain low interest rates purely through pledges if capital demand and mobilization sources remain mismatched.
"The SBV needs to monitor each bank segment rather than looking solely at averages. Banks experiencing temporary liquidity deficits require appropriate liquidity support tools. Banks cannot continually hike deposit rates simply to sustain asset expansion," Phuong said.
Therefore, banks' commitments to lower interest rates must be paired with monthly and quarterly funding plans, alongside contingency scenarios for deposit shifts.
Regarding the fact that actual rates exceed listed rates, Phuong warned that this creates major fallout in the form of distorted information. Regulators assume mobilization costs have fallen, when in reality banks are still "buying" capital at high prices.
Tuan Nguyen

