 Vietnamnet.vn

 Podcast


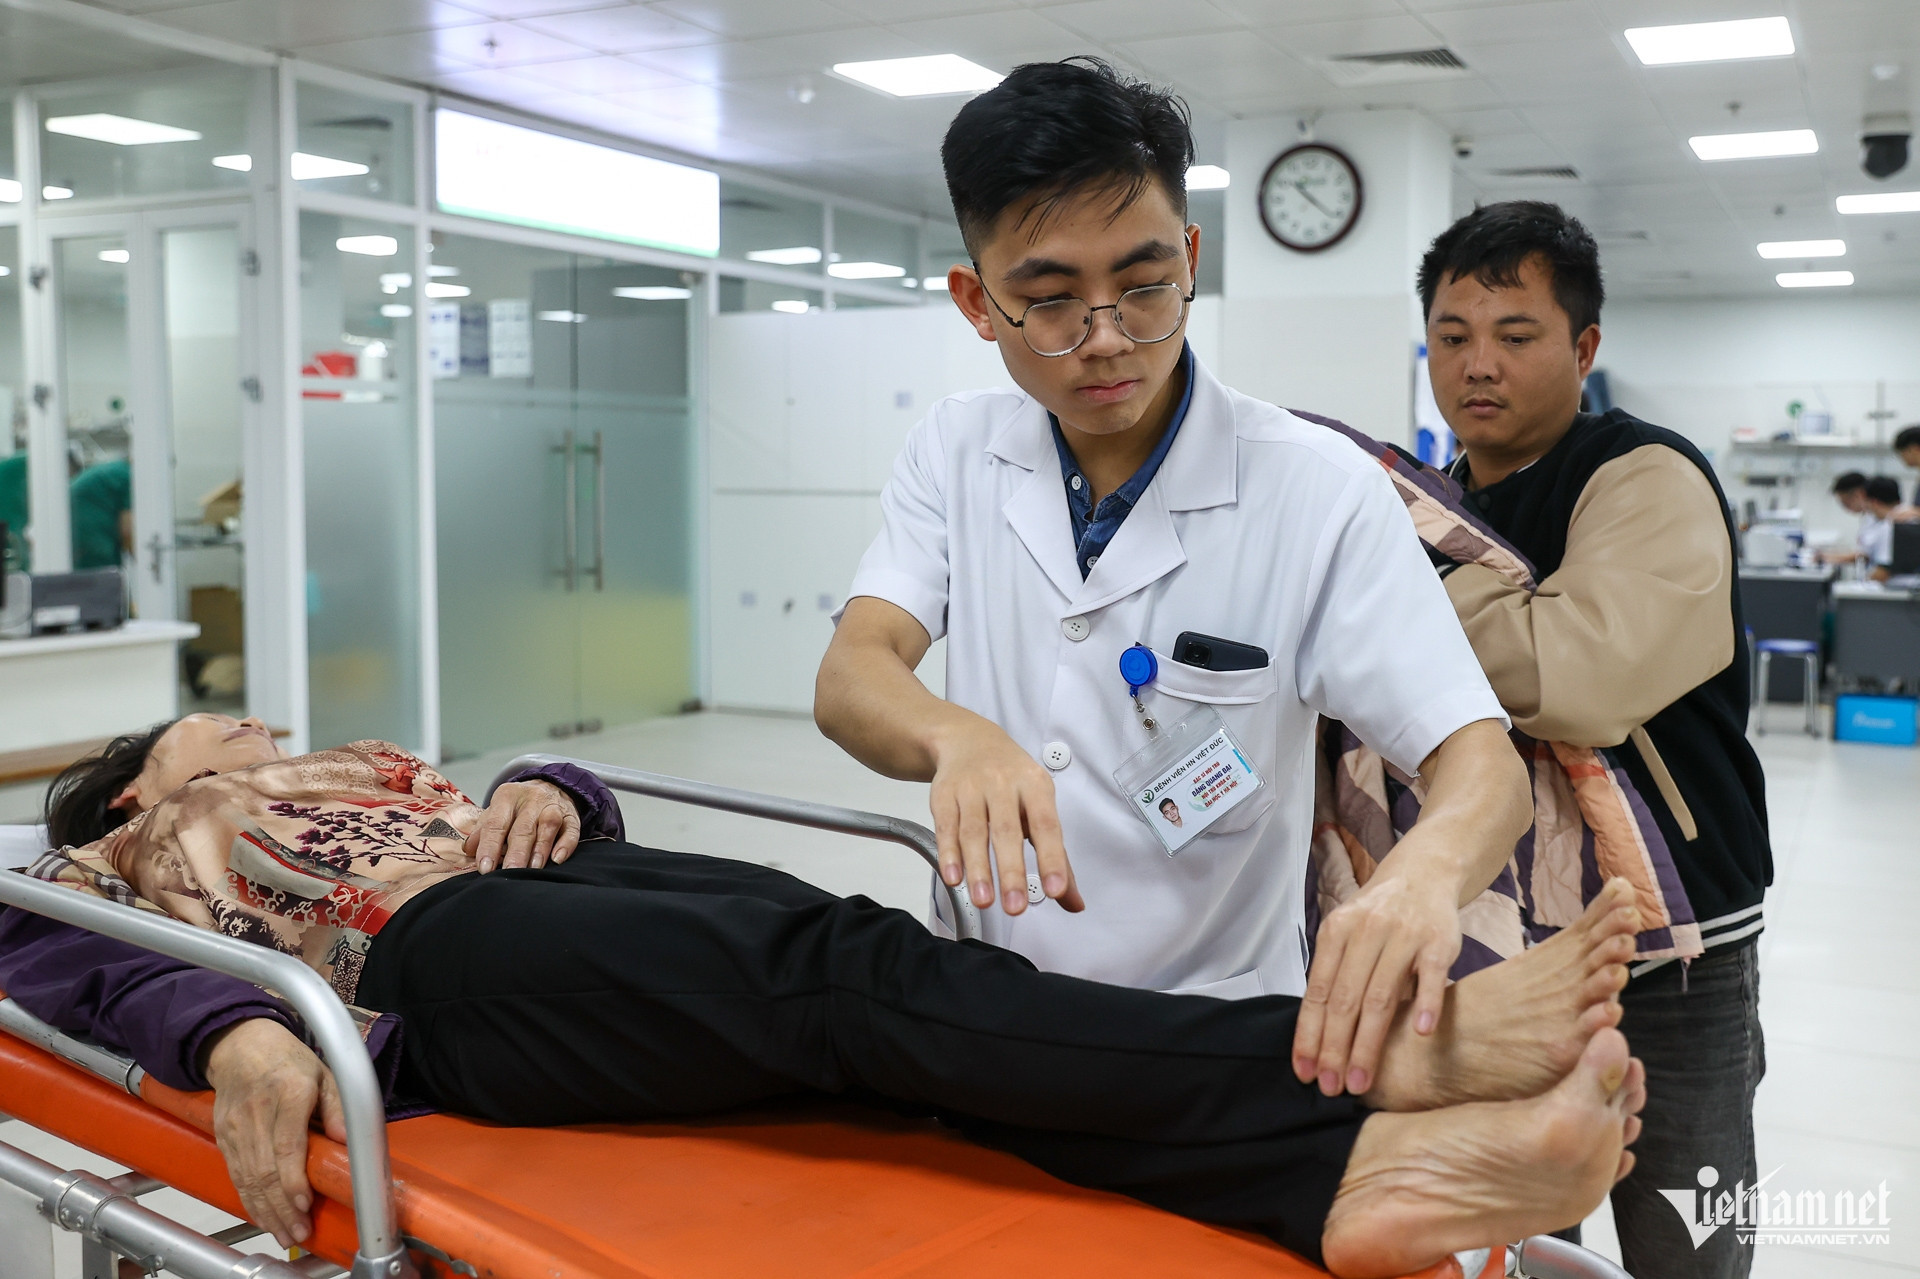
However, possessing a card with an 80 percent, 95 percent, or 100 percent benefit rate does not guarantee the Health Insurance Fund will cover the corresponding percentage of total medical bills. Actual coverage rates depend on the healthcare facility level, specific diseases, treatment modalities, covered service scopes, and how patients access care.
Quynh Anh, 40, discovered she had kidney failure following an examination at a private medical facility in Hung Yen Province. Anxious about her condition, she visited two major hospitals in Hanoi for further testing but received no health insurance coverage due to non-compliance with facility-level access regulations.
At Hanoi Kidney Hospital, medical results confirmed stage 3 chronic kidney failure, hypertension, suspected diabetes, and dyslipidemia. Following three months of treatment without metric improvements, she transferred to Bach Mai Hospital, where doctors ordered admission for a renal biopsy.
Her prior medical expenses totaled over VND15 million. In June, she returned to her initial registered healthcare facility in Hung Yen to request an official transfer to Bach Mai Hospital. Upon receiving the transfer approval to the specialized facility, Quynh Anh met the criteria for referred medical treatment.
Once she complied with transfer regulations, covered medical expenses were reimbursed by the Health Insurance Fund according to her benefit rate, reducing her out-of-pocket expense to a few hundred thousand VND per visit.
Quynh Anh's case illustrates a common misconception: receiving in-network medical treatment does not mean they can only seek treatment at the specific facility listed on their health insurance card.
Cases that appear to be out-of-network but qualify for full benefits
Nguyen Phu Tuong, a doctor at the General Planning Department of the National Children’s Hospital, said one of the most common cases eligible for full benefits involves emergency treatment.
Patients who need emergency care can go to any healthcare facility that has a health insurance contract. Whether a case qualifies as an emergency is determined by the treating facility based on the patient’s condition. In such cases, patients receive health insurance benefits in accordance with emergency-care regulations.
Another case involves patients who visit a basic-level healthcare facility, provided it falls under that fall under cross-level coverage regulations. Under current regulations, health insurance participants are entitled to benefits when receiving treatment at basic-level facilities in specified circumstances, including at facilities classified as district-level before January 1, 2025.
Therefore, seeking care outside an individual's registered facility or province does not automatically constitute out-of-network medical checkup.
For individuals working, studying, or temporarily residing in other localities also qualify for health insurance benefits when seeking care at designated local facilities, there is no need to return to their initial registration site.
Furthermore, patients seeking care at initially registered facilities receive standard coverage, while those undergoing inpatient treatment at basic-level facilities receive 100 percent of their entitled benefit rate. Certain inpatient treatments at specialized-level facilities also receive 100 percent coverage, depending on the facility type, patient category, and diagnosed condition.
Effective July 1, 2026, amended health insurance regulations further expanded benefits for self-referred patients, invalidating the misconception that self-referrals always result in forfeited insurance coverage.
A specialized exception applies to patients suffering from rare diseases, critical illnesses, or conditions requiring complex surgeries and high-tech procedures listed by the Ministry of Health.
Under Circular 01/2025/TT-BYT, patients diagnosed with diseases listed in Appendix I can directly access care at specialized-level facilities without completing standard transfer procedures.
For these cases, the Health Insurance Fund covers 100 percent of entitled benefits within the covered scope, encompassing designated cancers, cardiovascular conditions, blood disorders, neurological diseases, and renal failure.
Similar diagnoses may yield different benefits
A widespread misconception among patients is assuming that the same medical diagnoses guarantee identical health insurance reimbursements. In reality, financial benefits depend on the facility level, treatment format, and how the patient accesses the facility.
For example, two patients who both hold an 80 percent health insurance benefit rate and suffer from a condition requiring specialized-level care. Patient A receives a proper referral from a primary-level facility to a specialized hospital, securing 80 percent coverage for all eligible expenses from the Health Insurance Fund.
Patient B, by contrast, independently visits a specialized-level facility and falls under a category subject to a lower reimbursement rate because he has not followed the prescribed referral procedure.
If the applicable rule provides for reimbursement of 40 percent of the benefit rate for inpatient treatment, a patient whose benefit rate is 80 percent would receive coverage equivalent to 32 percent of eligible expenses. Current regulations set the 32 percent rate for patients receiving inpatient treatment at specified specialized-level facilities when their illness or disease group does not qualify for special provisions.
Vo Thu

