 Vietnamnet.vn

 Podcast


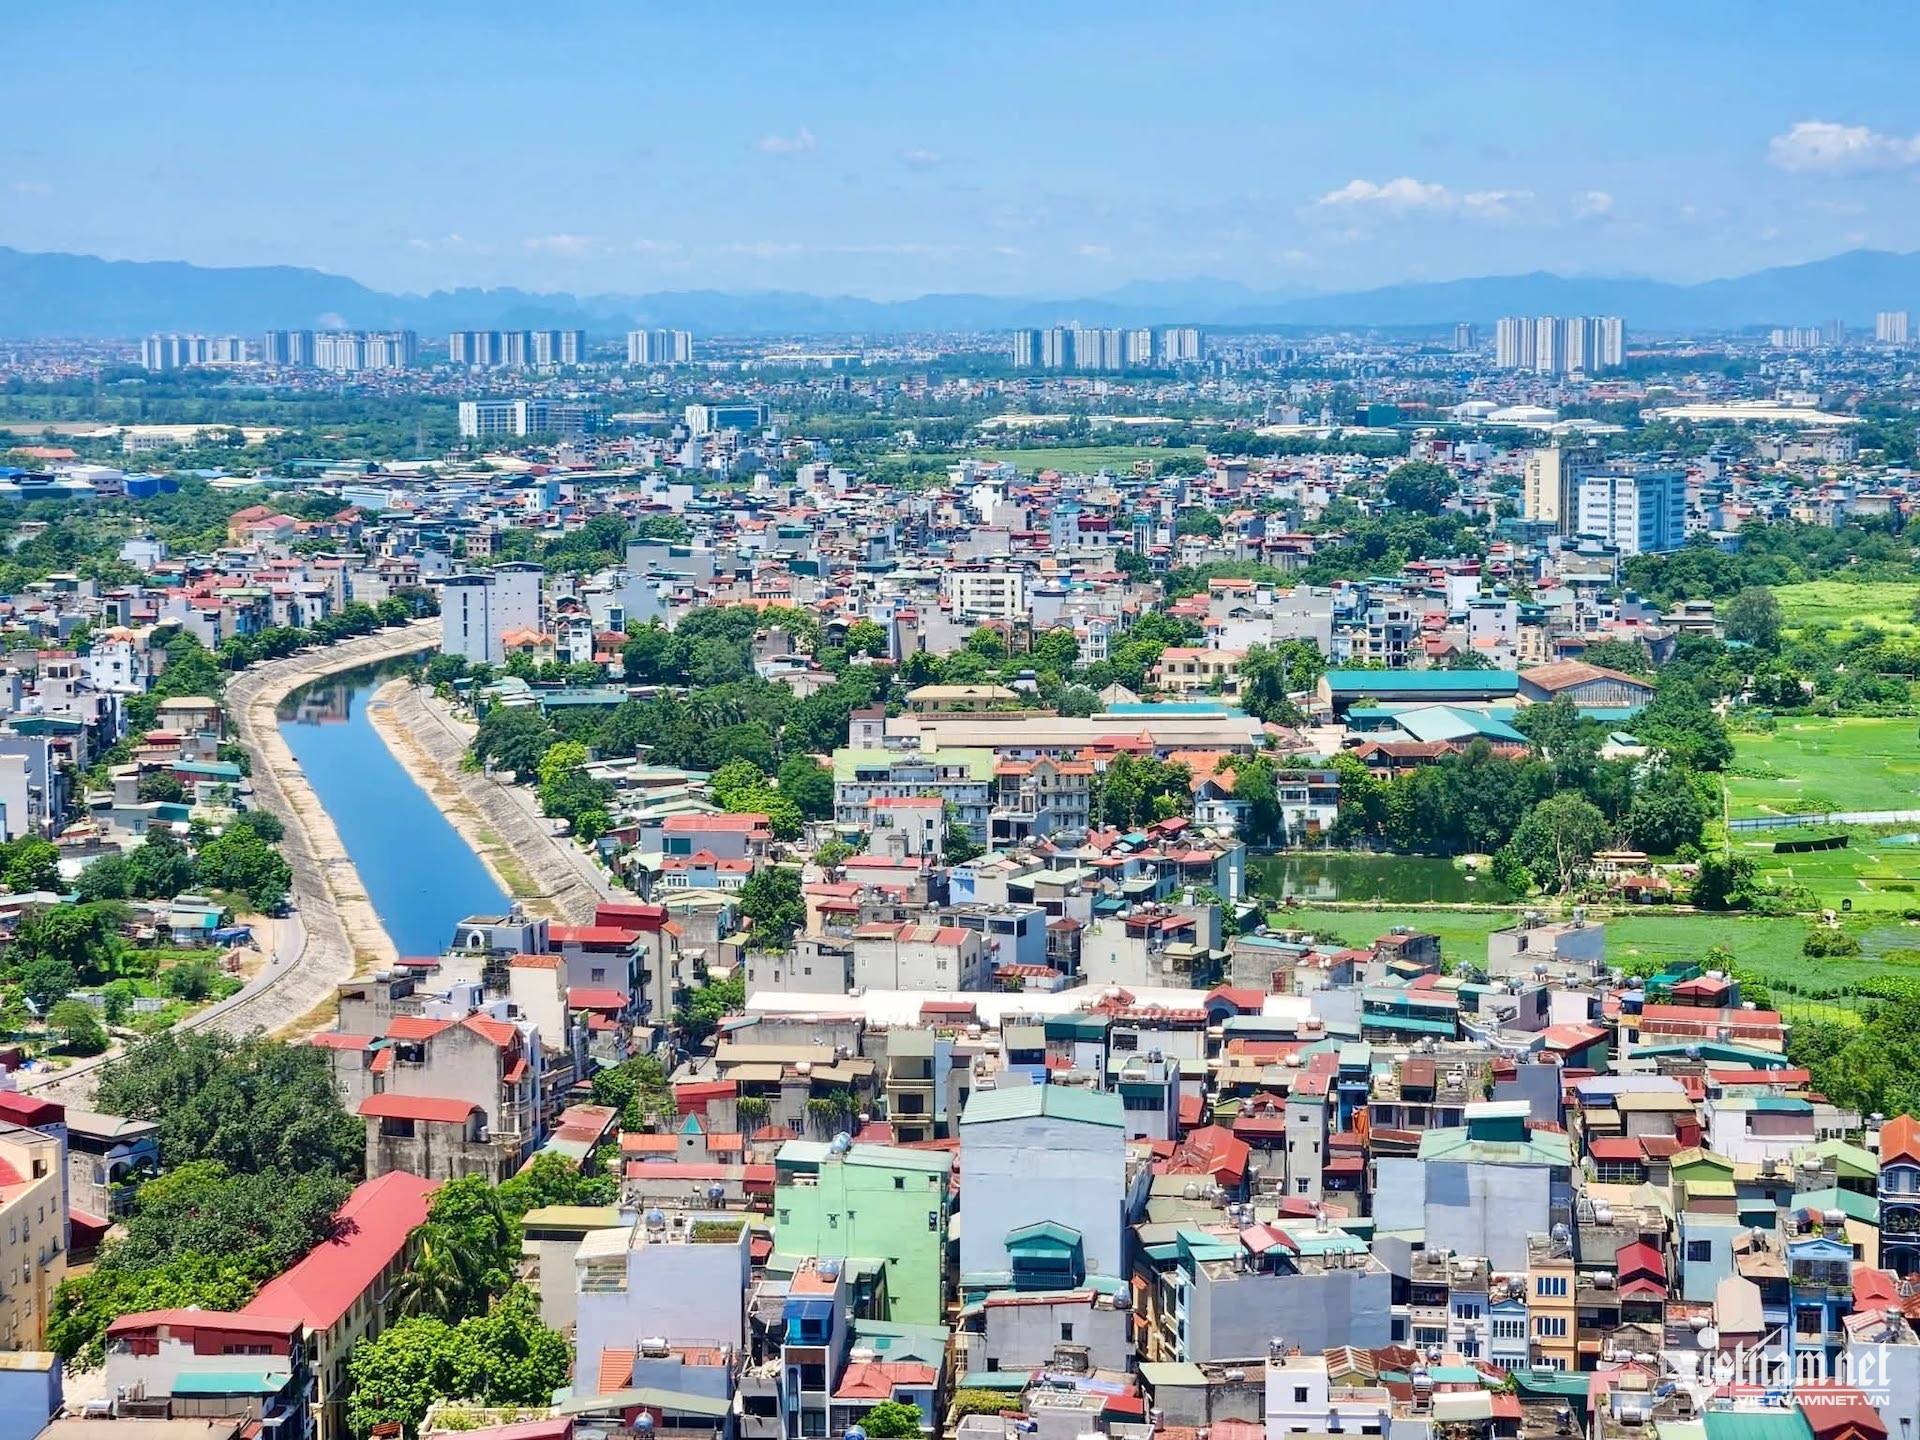
Weakening liquidity and rising project inventory, combined with borrowing pressures, could cause investors to cut prices to recover their capital.
Citing data from the Ministry of Construction's 9-month 2026 housing and real estate market report, the HCMC Real Estate Association (HoREA) highlighted emerging adjustment signals across both selling prices and market liquidity.
According to the report, overall transaction prices in Q3/2026 showed a slight downward trend compared to Q2. However, the magnitude of adjustments varied across different market segments and locations.
For apartments, prices edged down slightly, though baseline price levels remained anchored high in major urban centers. Rising construction costs and capital costs continued to exert pressure on selling prices.
In the villa and townhouse project segments, prices in several areas registered minor declines alongside sluggish liquidity. Buyers increasingly prioritized projects backed by clear legal status, completed infrastructure, and practical operational viability.
Notably, secondary market land plots remained under downward adjustment pressures. Weakened liquidity amid high capital costs prompted investors to shift toward end-use residential products offering transparent legality and stable utility.
Similarly, resort and hospitality real estate showed an uneven recovery. Certain projects recorded slight price drops, with transactions concentrating mainly on fully compliant products in prime locations managed by reputable operators.
Price movements paralleled a slump in transaction volume. According to HoREA referencing Ministry of Construction figures, the country recorded over 331,800 successful real estate transactions in the first nine months of 2026, including nearly 80,270 apartment and individual house units, alongside over 251,600 land plot transactions.
In Q3, the market logged approximately 92,000 successful transactions, reaching 92 percent of Q2 levels, representing an 8 percent decline.
Within this total, apartment and individual house transactions reached over 22,800 units, down roughly 14 percent quarter-on-quarter. Land plot transactions totaled over 69,150 lots, reflecting a 6 percent decrease.
Le Hoang Chau, Chair of HoREA, warned that declining purchasing power could leave real estate companies with capital tied up in assets and insufficient cash flow, weakening their liquidity or even making them unable to meet their obligations. This could have a domino effect on credit institutions in the coming period.
Reflecting real-world enterprise realities at a recent property price seminar, Pham Duc Toan, General Director of EZ Vietnam Real Estate Investment and Development JSC, noted a steep drop in market transactions. At his firm, transaction volume since the start of the year plunged by roughly 90 percent.
According to Toan, the market has virtually frozen across numerous segments. Transactions are heavily concentrated in social housing and secondary real estate within completed projects featuring stable resident communities. Select projects in this category recorded active transactions, primarily driven by steep price discounts.
Will financial pressures force price cuts?
Regarding the likelihood of further price declines, Tran Quang Trung, Business Development Director at OneHousing, noted that future price movements hinge on multiple variables, with the capital market wielding significant influence over price levels and buyer behavior.
According to Trung, pinpointing the market bottom is notoriously difficult, much like forecasting a stock market bottom. Distinct segments and investor groups will experience varying trajectories.
In the secondary market, attention must focus on highly leveraged investors who entered with initial equity ratios of roughly 20-30 percent.
As property prices decrease, this group faces mounting pressure if forced to liquidate assets to settle debt obligations. In a severe price downturn, their initial equity risks being heavily eroded or completely wiped out. Actual financial losses depend on outstanding loan balances, carrying costs, and final asset sales prices.
Debt payment obligations could force a subset of investors to discount prices to recover capital, particularly for assets failing to generate cash flow or lacking effective operational use.
For residential land and landed property, Trung anticipated potential price reductions. This segment previously operated with relative freedom. Investors buying land to subdivide or construct new houses for resale rarely benefited from specialized financial support packages.
According to the expert, the overheating phase during 2024-2025 pushed property prices sharply higher across many areas. Some investors bought land using borrowed money and then took on additional debt to build houses for resale.
In eastern Hanoi, including Long Bien, Dong Anh and Gia Lam, some investors adopted this model in the expectation that property prices would continue to rise.
However, as liquidity weakened, reselling properties became much more difficult than before. Investors facing large loans, high financing costs and extended holding periods may have to accept lower prices to find buyers.
Hong Khanh

