 Vietnamnet.vn

 Podcast


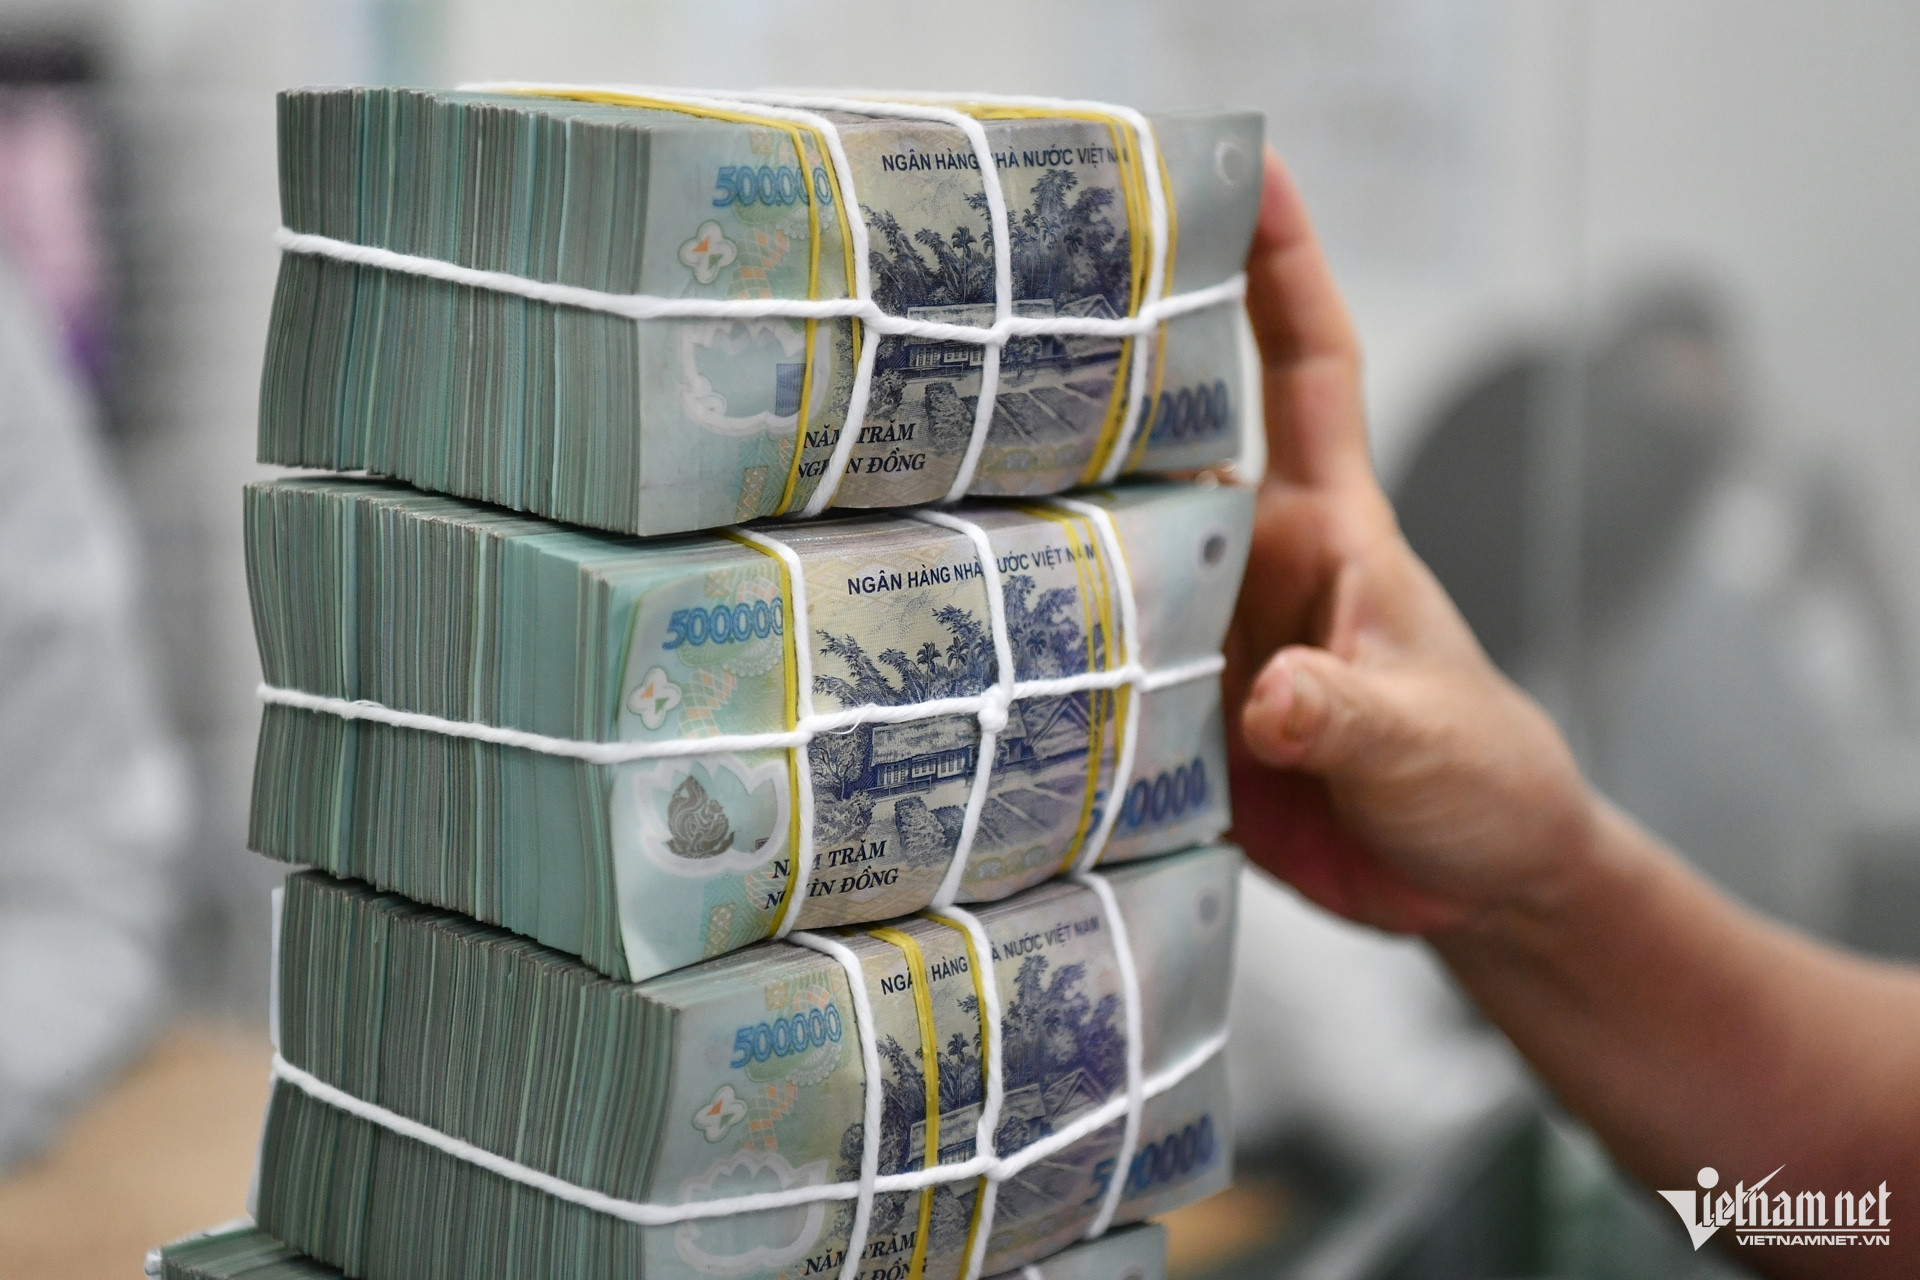
Following the Government's policy direction and the State Bank of Vietnam's instructions, the banking system is stepping up preferential lending programs to support SMEs and priority sectors. The Big 4 state-owned banks alone have set aside around VND220 trillion, with interest rates at least 1 percentage point a year lower than their average lending rates for loans of the same maturity.
Abundant capital, limited access
Lam Ngoc Tuan, director of Tuan Ngoc Agricultural Cooperative in HCMC, said the cooperative currently has a medium-term loan with an average interest rate of 8.5-9 percent a year. This rate acceptable given the cooperative's production capacity.
Regarding preferential credit programs for SMEs and priority sectors, Tuan said banks had proactively informed businesses about the cheap-loan packages and announced that they would begin accepting new loan applications in August. However, he said not every business has a chance to access cheap capital.
Hoang M.C., Executive Director of an import-export company in Nghe An, shared that the business has a medium-term loan at a state-owned bank with an interest rate of 8.6 percent per year and a 6-month loan at a commercial bank with an interest rate of 11.2 percent per year.
C said recently, some commercial banks have even warned that capital shortage pressure could cause lending interest rates to rise at the end of the year. Therefore, when asked about the ability to access cheap capital flows, C. answered briefly: "Difficult."
According to C., SMEs wanting to access cheap capital, especially capital from the state-owned banks, must have a good credit history, "beautiful" financial statements, and collateral of the right scale - something that not every business can meet.
This executive believes that falling interest rates do not mean businesses will increase their demand for loans. If interest rates decrease but orders are not yet available, or the production situation is gloomy, adding more financial leverage is something few businesses think about. Therefore, reducing interest rates does not necessarily create growth momentum for the SME sector.
Similarly, a representative of a packaging manufacturing business in HCMC reflected that the unit is taking out a mortgage loan at a foreign-capitalized bank. Although the interest rate is quite good compared to commercial banks, interest has also increased by 1 to 2 percent compared to June.
The executive worried that if the total credit packages worth VND220 trillion from the Big 4 group continue to operate under the old mechanism, capital is likely to flow back to the group of businesses that are already qualified, instead of reaching the right subjects who are thirsty for capital.
Dr. To Hoai Nam from Vietnam Association of Small and Medium Enterprises (VINASME), affirmed that the proportion of SMEs accessing bank capital remains at a low level, only about 20 to 25 percent. This is because lenders still require real estate as collaterals.
Nguyen Tuan Anh from RMIT University Vietnam assessed that the biggest bottleneck for SMEs lies in secured assets. The 2 percent interest rate support package under Decree 31/2022/ND-CP showed a low disbursement rate, partly because many businesses could not meet traditional credit standards.
Tuan pointed out the barriers making it hard for the SME sector to touch preferential capital flows.
First of all, many units lack accounting book transparency, leaving banks without a basis to evaluate financial capacity and decide credit limits. Next is the discrepancy in asset valuation, as banks usually only approve loans worth 70 percent of liquidation value.
In addition, limited management capacity, along with the habit of scattering cash flow across multiple accounts, makes it difficult for credit institutions to evaluate revenue strength.
To unblock cheap capital flows, Anh suggested drawing from the experience of Taiwan's Credit Guarantee Fund (SMEG) model (China), where the Government stands out to guarantee 80 to 90 percent of loan risks based on the feasibility of the business plan instead of mortgaged real estate.
At the same time, he believes the domestic banking system needs to step up cash-flow-based lending and apply alternative data sources, such as tax filing history, e-invoices, and revenue via accounts to score credit.
Nam also emphasized that commercial banks cannot be required to lower credit standards to bear bad debt risks, but they can completely change the way credit is evaluated.
Banks need to diversify appraisal criteria based on digital data, from operating cash flow through accounts, e-invoice history, actual contracts, to machinery systems, warehouses, and intellectual property rights.
Thu Ha

