 Vietnamnet.vn

 Podcast


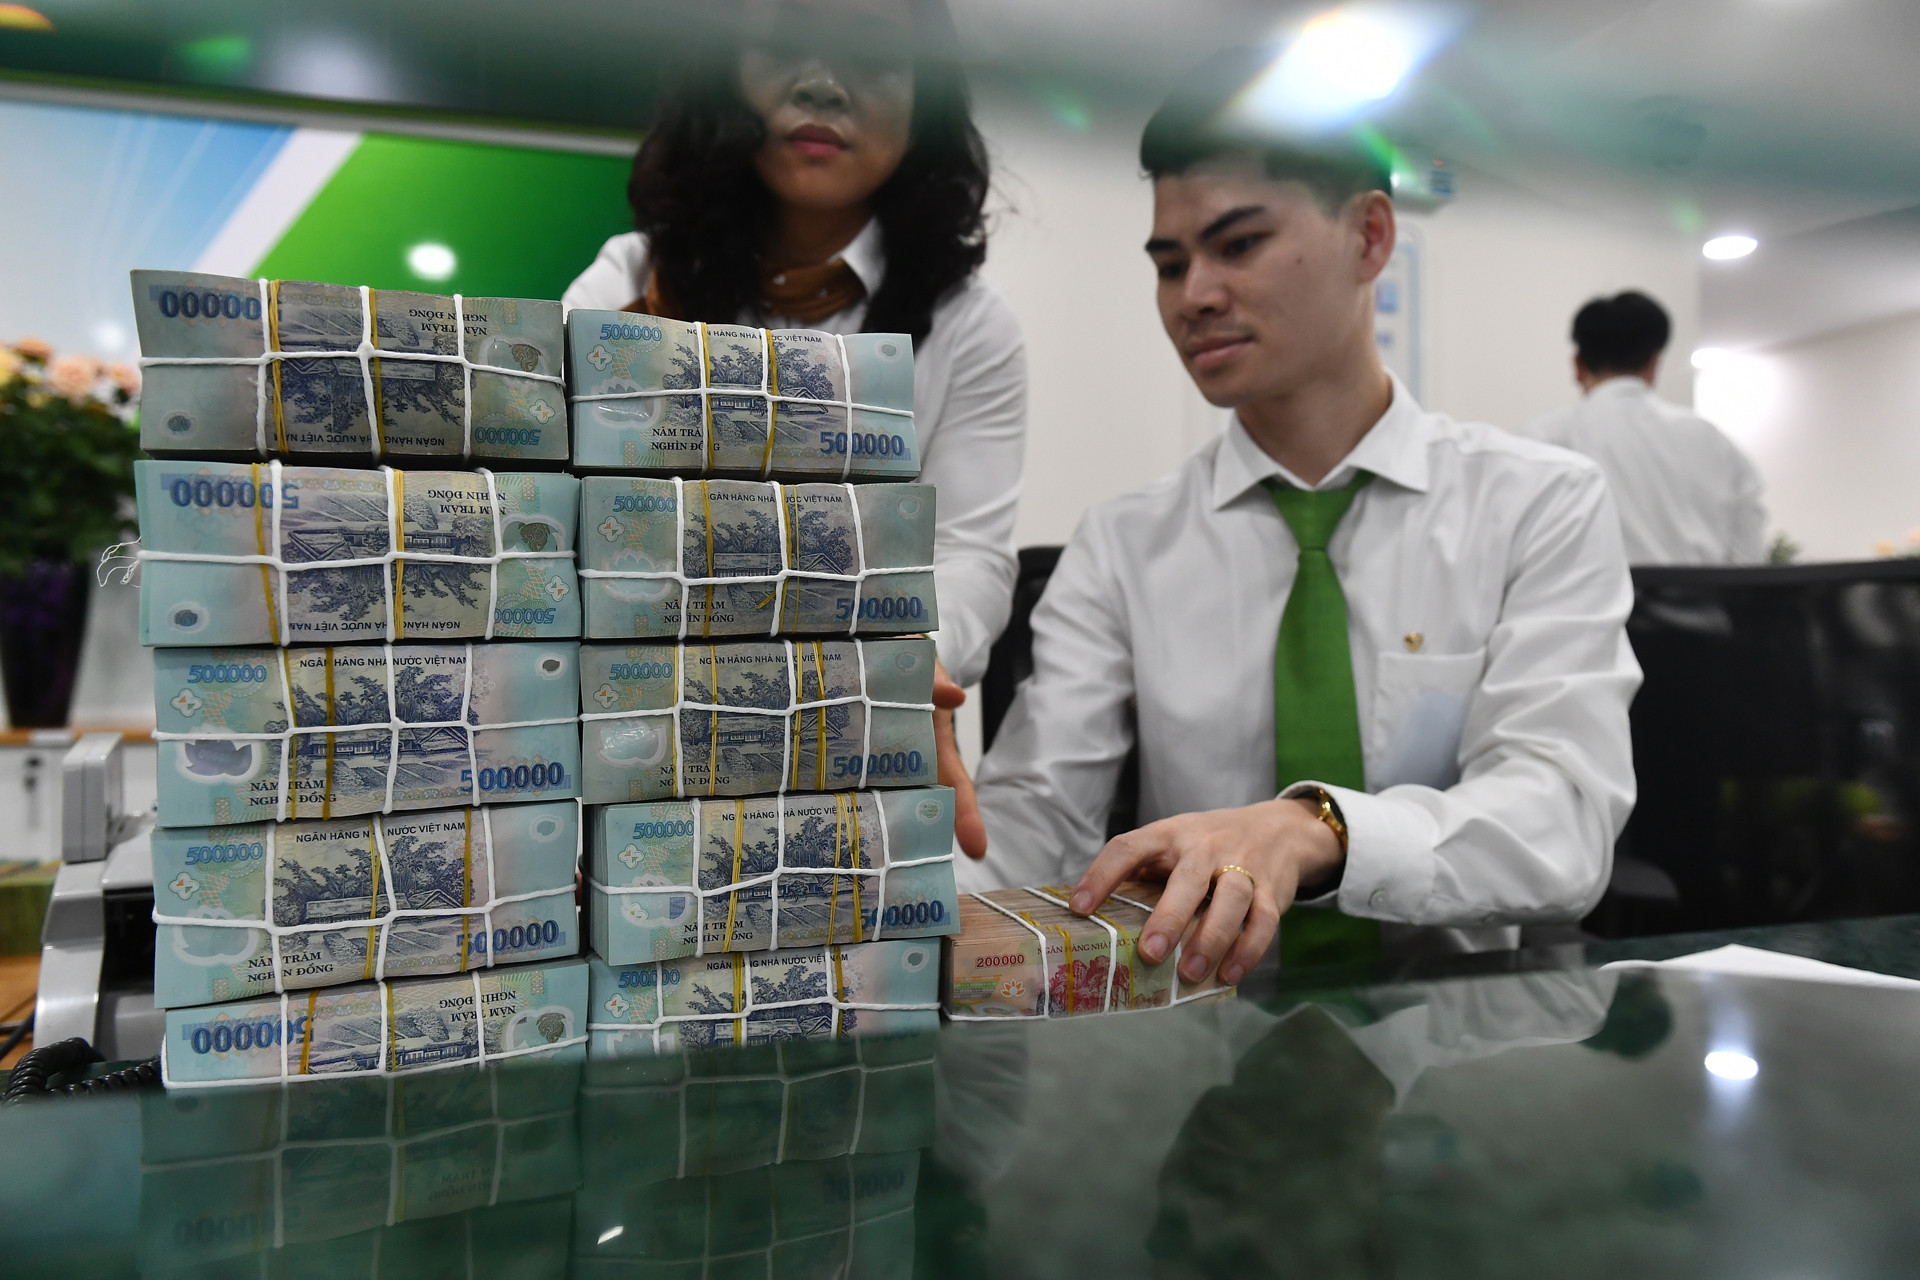
This presents a formidable test, yet it opens opportunities for the banking, securities, energy, infrastructure, power, gas, and electrical equipment sectors.
GDP grew by 8.18 percent in the first six months of 2026. To achieve the full-year growth target of 10 percent, second-half GDP must expand by 11.5–12 percent, based on estimates tied to periodic GDP scale. This imposes heavy demands on investment, consumption, and exports alike.
A primary challenge lies in securing long-term capital. Credit balance across the economy reached nearly VND20.3 quadrillion as of July 31, 2026, representing an 8.98 percent increase from the end of 2025.
Meanwhile, full-year 2025 credit expanded by about 19.2 percent, notably outpacing the deposit growth rate of 14.1 percent. This imbalance highlights that capital demand is expanding faster than deposit growth capacity.
The underlying issue is not a total absence of funds, but rather the challenge of mobilizing medium- and long-term capital on a scale large enough to meet investment demands. With credit-to-GDP already at an elevated level of roughly 150 percent, continuing to rely excessively on commercial banks leaves increasingly limited room for expansion.
The second challenge is electricity. The adjusted Power Development Plan VIII (PDP8) targets securing enough power for an economy growing at an average rate of around 10 percent per year during the 2026–2030 period. Commercial electricity demand for 2030 is targeted at 500.4–557.8 billion kWh.
This is a massive undertaking, as power demand is projected to grow by 10–12 percent annually, or even higher under high-growth scenarios. Vietnam must not only expand generation capacity, but also invest heavily in transmission grids, energy storage, and dispatch systems. The current plan sets a target for battery energy storage system (BESS) capacity at 10,000–16,300 MW by 2030.
Expanding capital channels
To address capital constraints, Vietnam is pursuing a multi-channel strategy rather than relying solely on bank credit.
Within the banking system, a wave of capital increases is underway. SHB received approval to raise its charter capital to VND53,442 billion; ACB has increased its capital to over VND58,000 billion; and OCB plans to issue nearly 399.5 million shares to raise its capital to VND30,625 billion. MB is also expanding capital, while VPBank aims for a charter capital exceeding VND106,200 billion, including a private placement plan for foreign investors.
The stock market is also expected to become an increasingly crucial channel for capital mobilization. FTSE Russell confirmed that Vietnam will be upgraded from a Frontier Market to a Secondary Emerging Market starting September 21, 2026.
Vietnam’s stocks will be incrementally added to the FTSE Global Equity Index Series across four tranches from September 2026 through September 2027.
This milestone is expected to unlock growth potential for securities firms such as SSI, VCI, HCM, MBS, and VND as market liquidity, margin balances, IPO activity, and capital raising improve.
Energy development
In terms of energy, the Ministry of Industry and Trade estimates total capital requirements for energy development in the 2026–2030 period at VND4.9–5.5 quadrillion.
This capital will flow into a wide array of sectors: LNG power, thermal power, hydropower, wind power, solar power, nuclear energy, power grids, and energy storage. Vietnam also aims to bring the Ninh Thuan 1 and 2 nuclear power projects into operation during the 2030–2035 period, with a combined capacity of 4,000–6,400 MW.
Actual investment scale is already massive. EVN alone disbursed VND125,778 billion for construction investment in 2025, up 14.7 percent from the previous year.
From this, a new investment cycle can take shape and create opportunities for various corporate groups.
In the banking sector, MBB, TCB, VCB, ACB, SHB, VPB, and OCB possess large capital bases and stand to benefit if credit demand continues to expand.
For the securities group, SSI, VCI, HCM, MBS, and VND are noteworthy thanks to their ability to benefit from the expansion of the capital market.
In power and energy, POW, NT2, REE, GEG, and QTP stand to benefit from rising power generation demand. The gas and LNG group, including GAS, PVS, and PVD, can benefit from gas-to-power chain developments and large-scale energy projects.
Manh Ha

