 Vietnamnet.vn

 Podcast


Lower funding costs to unlock capital for the economy
On October 18, 2026, the State Bank of Vietnam (SBV) issued Official Letter No. 9608/NHNN-CSTT, setting out measures for credit institutions to help maintain macroeconomic stability, control inflation, support economic growth and safeguard the financial system.
A day later, the central bank met with commercial banks to reinforce its interest rate directives and demand concrete action to bring borrowing costs down for businesses and households.
Under the instructions, credit institutions must strictly follow the interest rate policies of the government, the Prime Minister and the SBV. They are required to proactively cut operating costs, share profits and implement coordinated measures to lower interest rates.
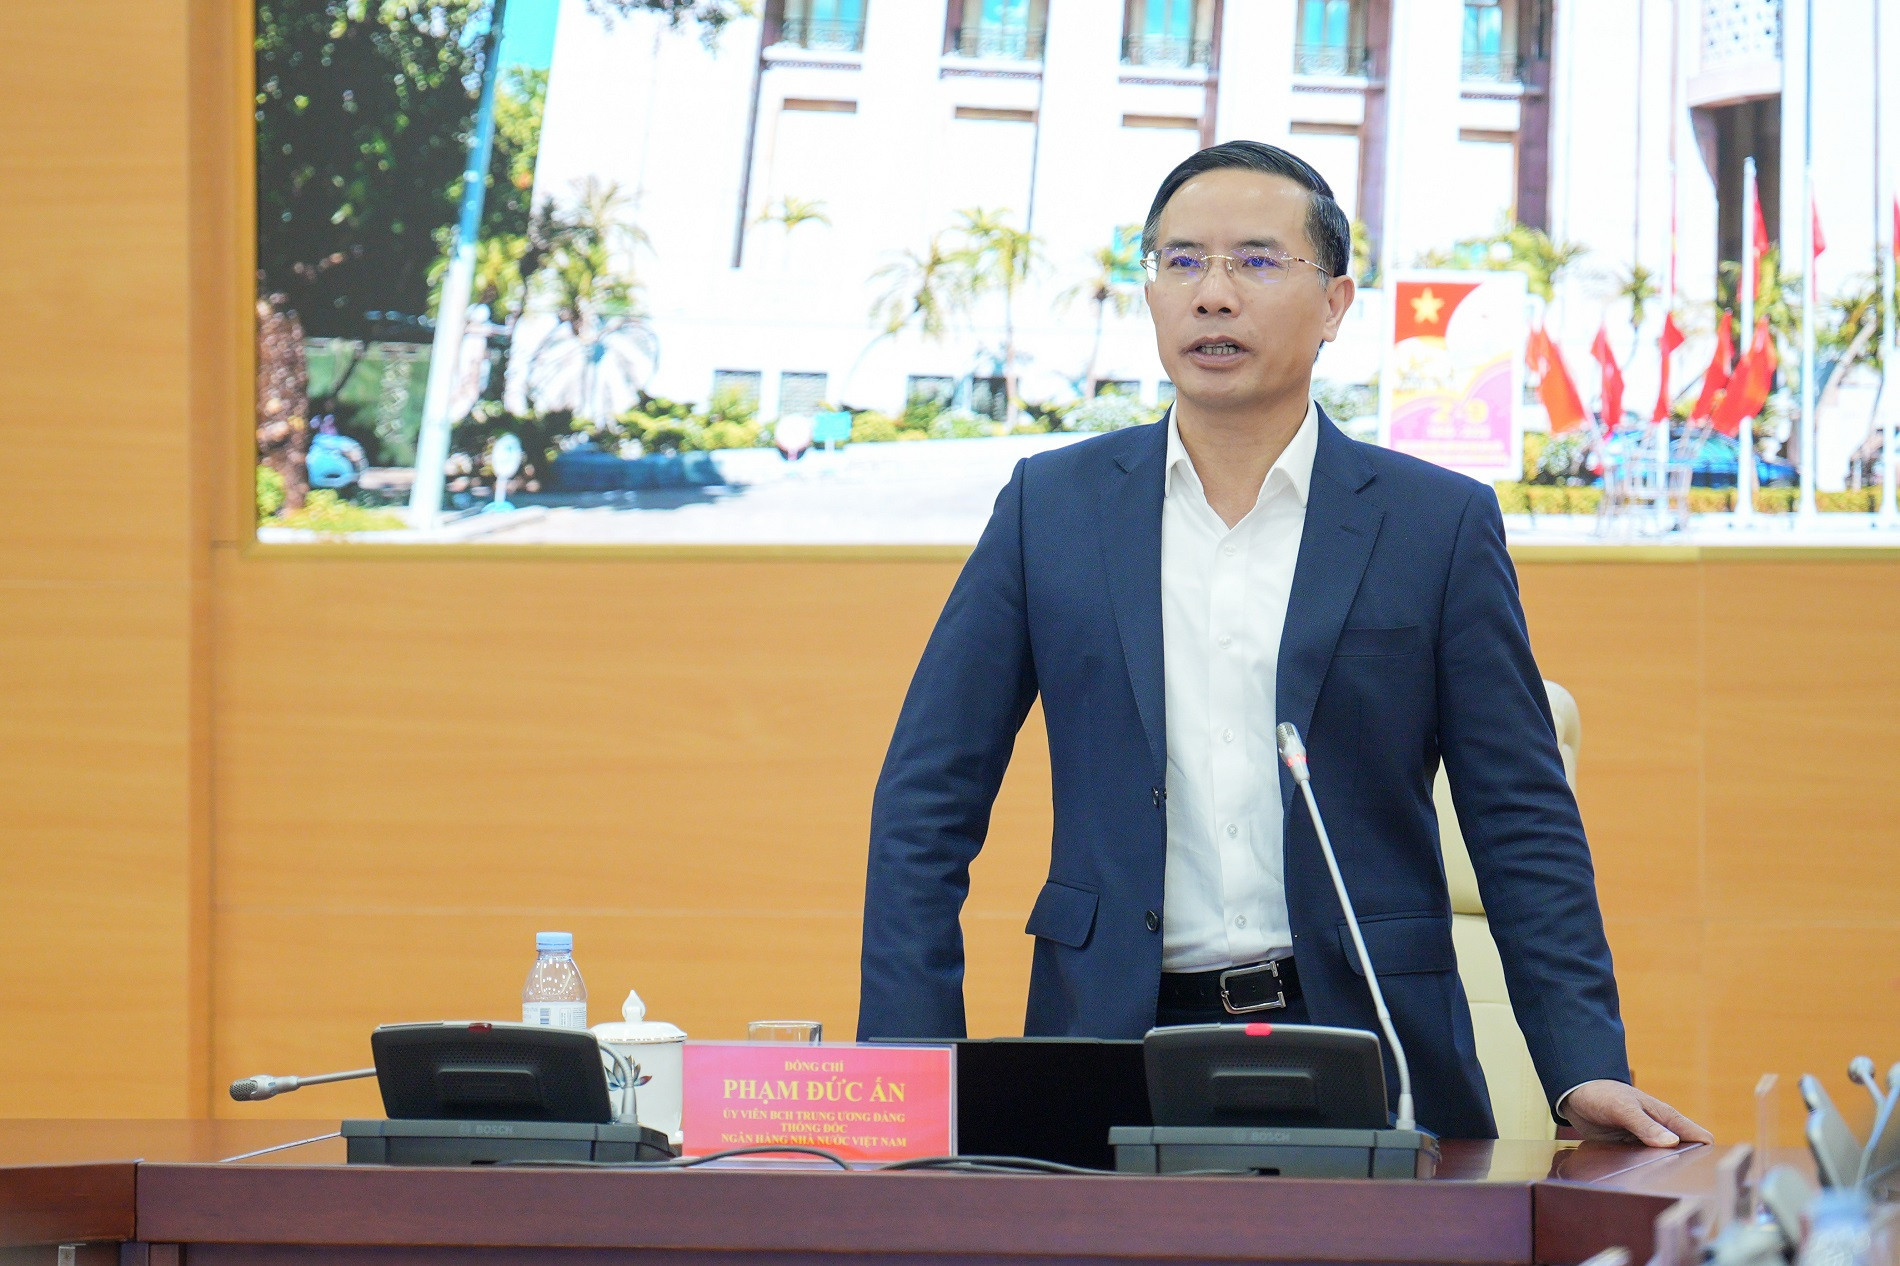
As an immediate step, banks must reduce their posted deposit rates for terms of six months or longer by at least 0.5 percentage points per year. They must also lower lending rates, targeting reductions of 1.5-2 percentage points per year for production, business activities and priority sectors.
The SBV has explicitly warned banks against competing aggressively to raise deposit rates, which could lead to unhealthy competition and destabilise the money market.
The directive comes as Vietnam seeks to sustain economic growth, with borrowing costs remaining a significant factor affecting businesses' ability to recover, invest and expand operations.
More affordable credit could ease financial pressure on companies, improve access to funding and enable businesses to pursue investment and production expansion plans.
Several major commercial banks have responded promptly to the central bank's instructions.
Le Ngoc Lam, Chairman of the Board of Directors of the Joint Stock Commercial Bank for Investment and Development of Vietnam (BIDV), said the bank had committed to immediately launching a credit package worth approximately VND100 trillion (US$3.8 billion).
The package will offer loans with terms of up to six months for production, business activities and priority sectors.
BIDV plans to cut lending rates by 1.5-2 percentage points, bringing rates under the programme to 6-7% annually, depending on loan maturity.
To fund the initiative, the bank will reduce operating expenses and deposit rates, freeing up resources to support businesses. Lam said BIDV expected to forgo approximately VND500 billion (US$19 million) in income as a result of the programme.
At Asia Commercial Joint Stock Bank (ACB), CEO Tu Tien Phat said the bank had already adjusted its deposit rates under a new interest rate schedule in line with government and SBV policy.
ACB is also continuing preferential lending programmes for businesses, offering interest rate reductions of 1.5-2 percentage points.
An earlier ACB programme offering a one-percentage-point interest rate reduction had disbursed approximately VND5 trillion (US$190 million).
An ACB representative also described the possibility of reducing credit growth quotas for non-compliant banks as a strong measure to reinforce market discipline, stressing that all lenders should take the central bank's directives seriously.
Economist Nguyen Tri Hieu said the interest rate cuts were necessary to support production and business activities and help Vietnam meet its economic growth objectives in 2026 and beyond.
However, he cautioned that the effectiveness of the policy would depend not only on how much rates were reduced, but also on whether capital reached the right borrowers, met genuine financing needs and supported sectors that generate real economic value.
Lower interest rates must not compromise credit quality
A key feature of Official Letter No. 9608/NHNN-CSTT is that the interest rate reductions are accompanied by strict requirements for risk management and banking safety.
The SBV has instructed credit institutions to pursue safe and effective credit growth, directing capital towards production, business activities, priority sectors and major drivers of economic expansion.
Priority should also be given to feasible, strategically important projects that contribute to socioeconomic development.
Crucially, the central bank has made clear that lenders must not relax credit approval standards or sacrifice loan quality simply to expand their lending portfolios.
Banks are required to strengthen credit assessments, verify borrowers' genuine financing needs and closely monitor lending to potentially risky sectors, as well as customers and groups of related borrowers with large outstanding debts.
They must also improve collateral management, closely track non-performing loans and make adequate, timely provisions for potential credit losses.
Hieu said lower interest rates could encourage credit expansion, but this should not be confused with a relaxation of lending conditions.
Maintaining sound credit standards, he argued, was essential to preventing bad debts, limiting capital flows into speculative and high-risk activities, and protecting the stability of the banking system.
He also warned that banks needed to maintain reasonable profitability.
Excessively aggressive lending rate cuts could undermine bank earnings and, in turn, weaken the financial institutions responsible for supplying capital to the wider economy.
From this perspective, interest rate management involves more than simply reducing borrowing costs. Policymakers must balance the interests of businesses, the financial capacity of credit institutions and the need for money market stability.
Lower rates should therefore be supported by reduced operating expenses, stronger governance and more diversified revenue streams.
Such measures would give banks greater room to offer affordable credit through improved efficiency rather than relying solely on narrower profit margins.
The SBV has also instructed lenders to maintain an appropriate balance between deposit mobilisation and lending, manage liquidity risks, limit maturity mismatches and increase the share of medium- and long-term funding.
These requirements are intended to ensure that banks can meet the economy's financing needs while preserving their ability to meet payment obligations and maintain stable operations.
The central bank has further emphasised the accountability of senior executives at credit institutions for implementing interest rate directives and ensuring safe, efficient banking operations.
Banks that fail to comply with interest rate instructions or engage in unhealthy competition that destabilises the market could face regulatory measures.
Depending on the nature and severity of the violations, the SBV may consider adjusting their credit growth quotas for the remainder of 2026, assigning lower credit growth limits in 2027 or requiring them to meet prudential ratios stricter than the standard regulatory thresholds.
Linking interest rate reductions to management accountability and potential sanctions is expected to strengthen policy implementation, discourage unfair competition and reinforce market discipline.
Beyond supporting businesses and economic growth, interest rate reductions must also be assessed against broader macroeconomic objectives, particularly inflation control and exchange rate stability.
Hieu identified inflationary pressure as an important consideration in implementing the rate-cutting policy.
Credit institutions must therefore reduce interest rates by proactively lowering costs, improving operational efficiency and sharing profits reasonably, while maintaining sound credit assessment, risk management and lending standards.
For policymakers, closely monitoring money market conditions, inflation and exchange rate movements will be essential to ensuring that measures designed to stimulate growth do not undermine Vietnam's macroeconomic stability.
Tuan Nguyen

