 Vietnamnet.vn

 Podcast


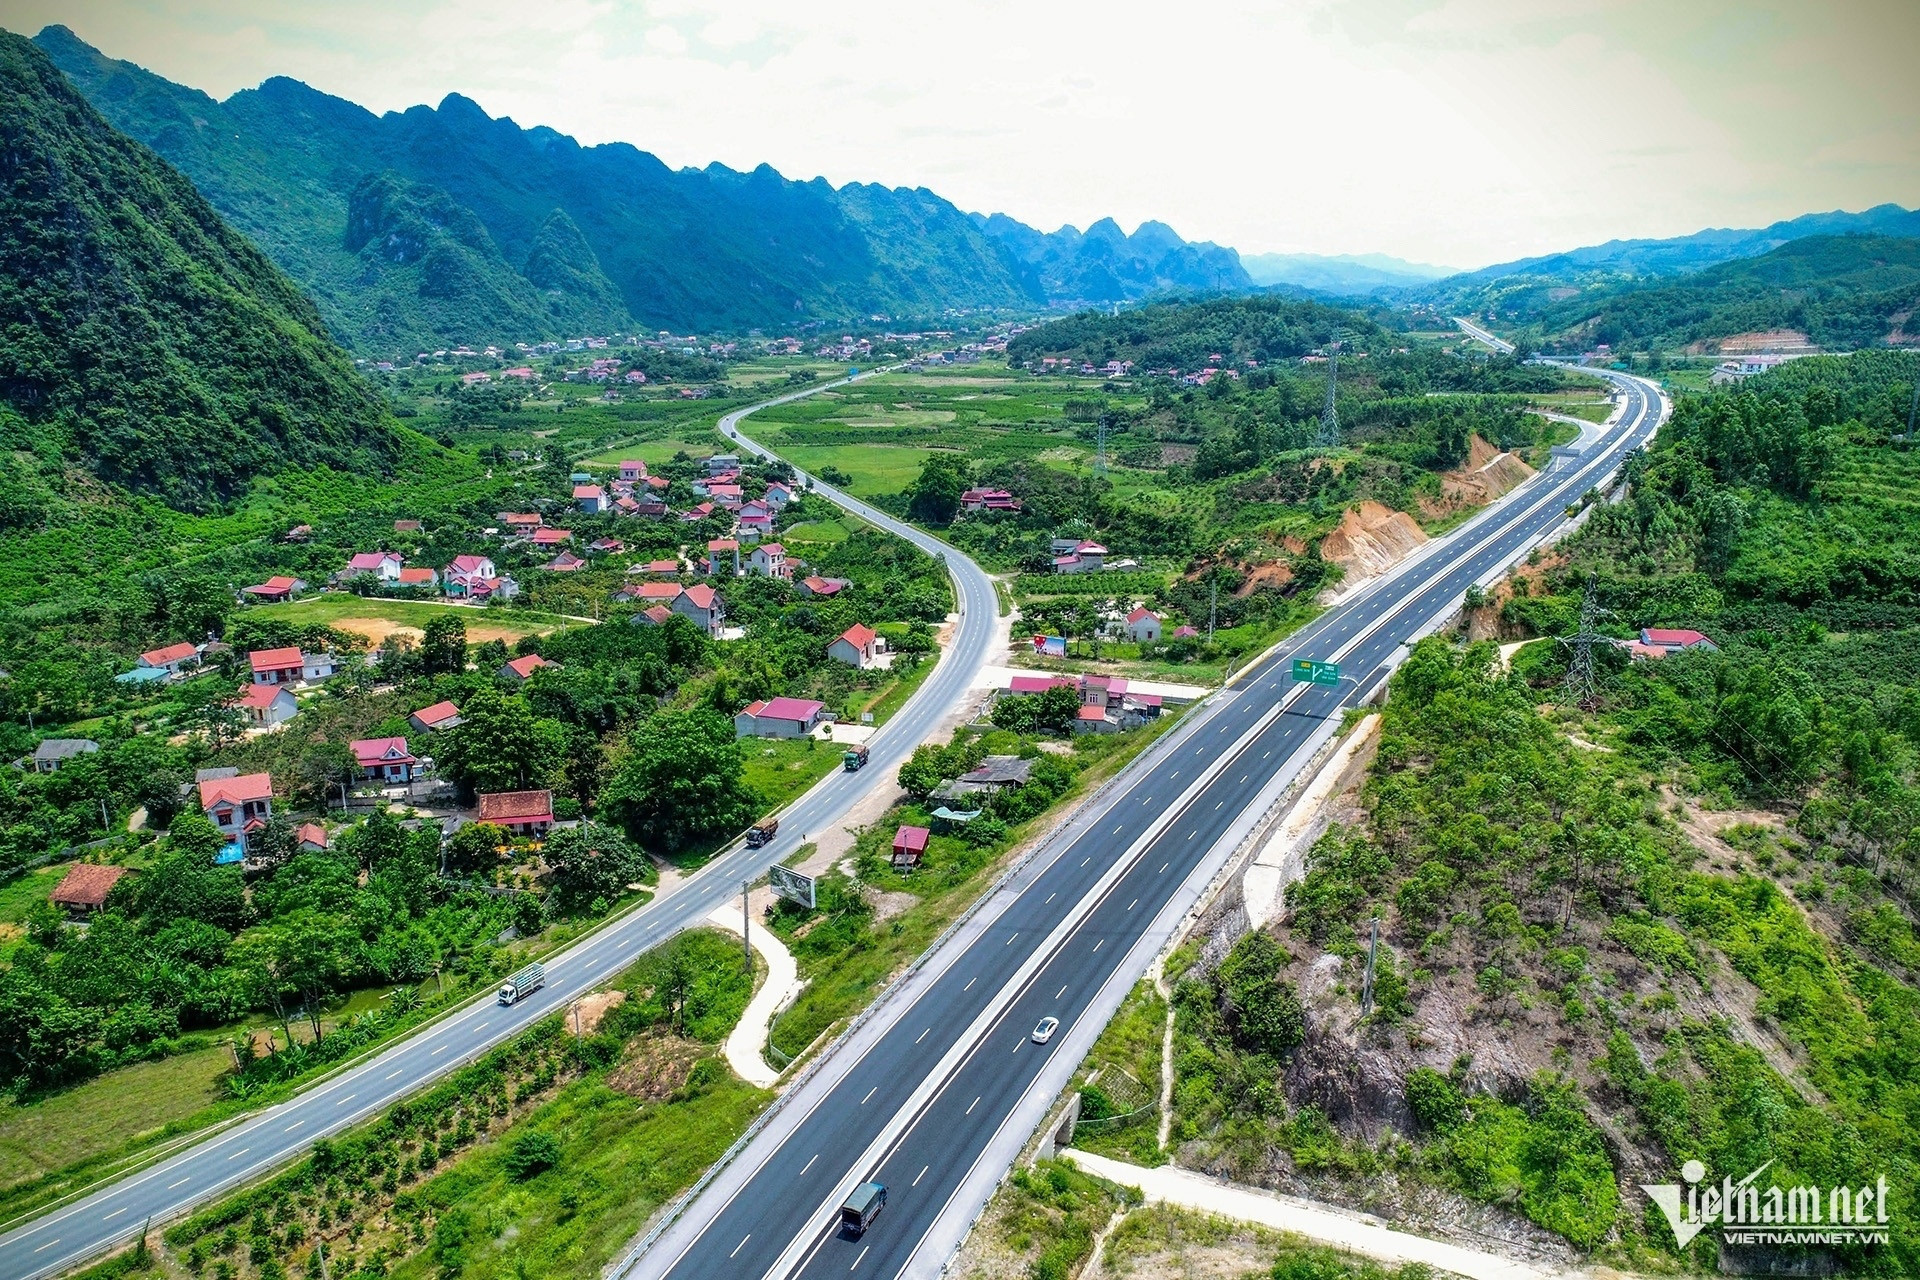
Vietnam's Ministry of Construction has included 29 expressway projects under the public-private partnership (PPP) model in its investment promotion portfolio for 2026-2030, with preliminary capital requirements totaling nearly VND 923 trillion ($35 billion).
The projects span several regions, ranging from the expansion of the eastern North-South Expressway and development of Ring Road 5 around the Hanoi Capital Region to new routes connecting the Central Highlands and the Mekong Delta.
Given the enormous investment requirements, the challenge goes beyond finding investors. Vietnam also needs to establish financing mechanisms attractive enough to secure long-term capital.
Expressway projects typically require substantial upfront investment during construction, while revenue only begins flowing once the roads become operational. Investors may have to wait decades to recover their capital, with returns exposed to fluctuations in traffic volumes and toll collection policies.
Banks face constraints in providing long-term financing
Nguyen Viet Long, Deputy General Director of international consulting firm Ernst & Young (EY), said the ability to mobilize capital for expressway projects depends on the quality of project preparation, the legal environment and how risks are allocated between the government and private investors.
Equity capital and bank loans remain the two main sources of financing. However, approximately 75-80% of deposits in Vietnam's banking system are short-term, while expressway projects may take decades to generate sufficient returns to repay their investment costs.
According to Long, Vietnam needs to diversify its funding sources by expanding access to project company bonds, commercial credit from engineering, procurement and construction (EPC) contractors, insurance companies, pension funds, infrastructure investment funds and development finance institutions.
Among these options, bonds could play an important role in refinancing projects after construction is completed, when construction risks have diminished and operating cash flows can be verified.
Project companies could issue bonds to replace part of their bank borrowing, freeing up credit capacity for new infrastructure developments.
However, being eligible to issue bonds does not necessarily mean a company will successfully raise capital. Investors still need to assess projected cash flows, financial strength and mechanisms protecting creditors.
Developing the bond market therefore requires stronger supporting services, including credit ratings, financial advisory, underwriting, auditing and independent monitoring.
Another supplementary financing option involves EPC contractors allowing project developers to defer payment of part of the construction costs until after project acceptance.
This approach could ease initial funding pressure but cannot replace equity contributions or long-term financing.
Revenue shortfalls threaten project viability
Beyond the challenge of raising capital, revenue uncertainty is another major risk that could directly affect the financial viability of PPP expressway projects.
Tran Hoai Nam, Deputy Director of VietinBank's Corporate Banking Division, said banks do more than provide loans. They also arrange financing, share risks, manage cash flows and monitor project implementation.
As of August 31, 2026, VietinBank had outstanding loans totaling VND 36.215 trillion ($1.37 billion) across 26 PPP projects, representing 1.72% of the bank's total outstanding credit.
For the Ho Chi Minh City - Trung Luong - My Thuan Expressway alone, VietinBank and five other banks have jointly committed VND 27.092 trillion ($1.03 billion) in financing, including VND 5.4 trillion ($205 million) committed by VietinBank.
Drawing on the bank's experience financing infrastructure projects, Nam said many PPP developments have encountered debt repayment difficulties because actual operating conditions differed from their original financial projections.
One particularly significant risk is that toll revenues may fall below expectations when parallel roads or bypasses are introduced, or when changes in transport planning and traffic management divert vehicles away from build-operate-transfer (BOT) expressways.
Delays in adjusting toll rates according to contractual schedules, along with slow disbursement of approved government budget support, can also put pressure on project companies' cash flows.
Nam said the government needs to maintain consistency in transport planning and carefully assess how traffic management decisions affect existing PPP projects.
He also called for faster auditing, timely determination of revenue shortfalls and implementation of risk-sharing mechanisms in accordance with regulations.
For their part, private investors must contribute sufficient equity, strengthen their financial capacity and improve risk management.
Investment plans should be based on realistic revenue forecasts rather than relying too heavily on expectations of continued traffic growth.
With nearly VND 923 trillion in planned investment across 29 expressway projects, Vietnam's ability to attract private participation will depend heavily on how risks are shared among the parties involved.
Investors need confidence that they can recover their capital, banks must keep credit risks under control, and the government must ensure stability in planning and policy.
Achieving that balance will be essential if Vietnam is to turn its ambitious expressway investment portfolio into financially viable projects that can move from planning to construction.
Vu Diep

